
Technology added $586 billion to the S&P 500 today. Five chipmakers accounted for $320 billion of it.
Published · 3 min read
sectorstechnologysemiconductorssp500federal-reserve
The S&P 500 rose 1.14% on 17 September, but Technology did nearly all of it: the sector added $586.2 billion, with Nvidia, Micron, AMD, Intel and Broadcom responsible for $320.3 billion of that as chip stocks extended a rebound from Wednesday's Fed-driven selloff.
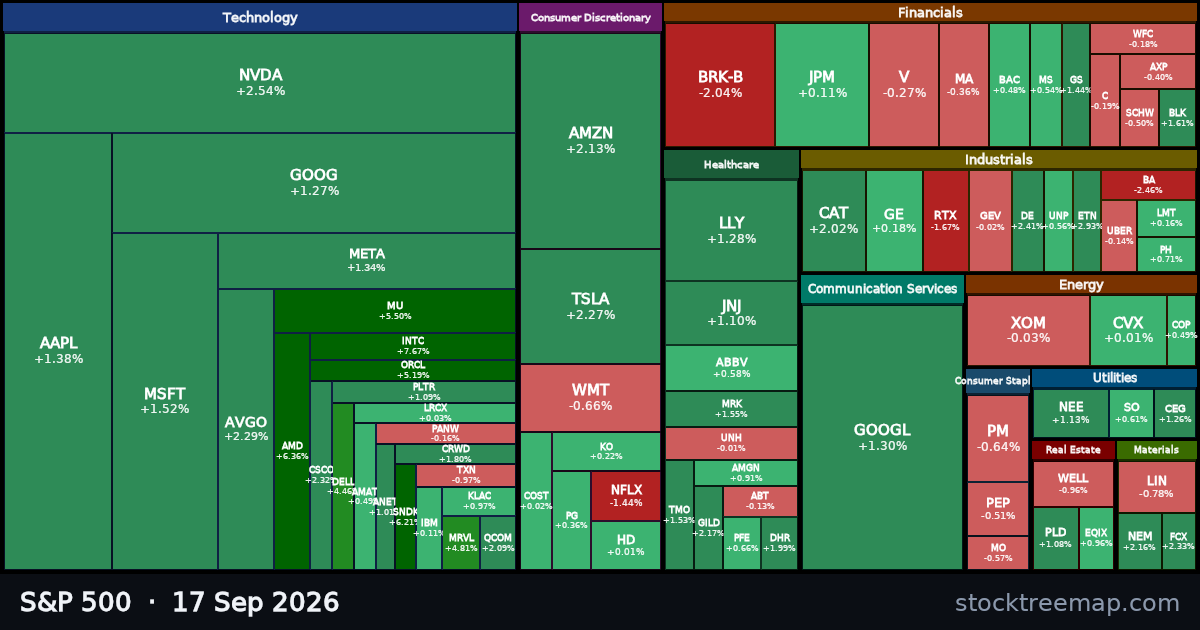
Technology added $586.2 billion to the S&P 500 on 17 September, the sector's biggest single-day move — up or down — of any session in our data since the start of the month, on a day the index itself closed up 1.14%.
Five stocks, more than half the gain
$NVDA alone added $131.4 billion, up 2.54% and the single largest dollar gain of any S&P 500 stock on the day. $MU rose 5.50% ($57.5 billion), $AMD gained 6.36% ($53.2 billion), $INTC rose 7.67% ($41.0 billion), and $AVGO added 2.29% ($37.2 billion). Together the five accounted for $320.3 billion of the sector's $586.2 billion gain — 55%.
The rally reached beyond the largest names, too: $SMCI rose 9.50% ($2.3 billion), $HPE gained 7.96% ($6.0 billion), $WDAY added 6.14% ($2.8 billion) and $HPQ rose 5.99% ($1.8 billion) — hardware and software both, not just the chipmakers at the center of it.
Yahoo Finance described the move as a chip rebound "reaching a third session," and MarketWatch reported Micron and Intel were both "furthering their strong comebacks." Barron's tied Thursday's Micron gain to comments from Intel's CEO warning on memory-chip supply — a scarcity signal that tends to lift both companies rather than pit one against the other.
Our own numbers back the multi-session framing for at least one of the five. $AMD closed up 2.19% on 15 September and 1.65% on 16 September before Thursday's 6.36% — three straight gains. $INTC's run in our data is shorter: down 0.05% on the 15th, then up 4.03% and 7.67% in the two sessions since.
Coming off a Fed-driven selloff
Those gains followed the Federal Reserve's rate decision on 16 September, when the central bank raised its key rate for the first time since 2023 — a hike, not the cut some had been debating. CNBC reported President Trump said he told the Fed's Kevin Warsh to back the hike anyway, saying opposition "wasn't going to matter," while AP News described the move as defying White House demands for a cut. The S&P 500 fell 0.44% cap-weighted on the day of the decision, on top of a 0.45% decline the session before.
Thursday's rebound tracked what CNBC described as retreating oil prices and bond yields following the rate scare. It showed up broadly across the index: ten of the S&P 500's eleven sectors closed higher.
| Sector | Change (cap-weighted) | Dollar change |
|---|---|---|
| Technology | +2.16% | +$586.2B |
| Consumer Discretionary | +0.99% | +$87.9B |
| Healthcare | +0.65% | +$40.5B |
| Communication Services | +0.48% | +$25.5B |
| Utilities | +0.87% | +$11.3B |
| Energy | +0.55% | +$12.9B |
| Industrials | +0.25% | +$13.2B |
| Materials | +0.59% | +$7.0B |
| Real Estate | +0.39% | +$4.7B |
| Consumer Staples | +0.05% | +$0.7B |
| Financials | -0.07% | -$6.3B |
The one sector that didn't join in
Financials was the exception, cap-weighted down 0.07% and $6.3 billion — a modest slip that hides a sharper move underneath. Berkshire Hathaway's Class B shares fell 2.04% and lost $22.7 billion, the index's single largest dollar decline of the day; MarketWatch noted the stock underperforming its peers without attaching a specific catalyst, and we found none in the headlines either. Most other Financials names were positive enough to nearly offset that loss at the sector level.
Communication Services carried a separate story. The sector rose 0.48% overall, or $25.5 billion, but T-Mobile fell 5.57% and lost $10.5 billion on its own — the index's second-largest dollar decline of the day — after Yahoo Finance reported renewed competitive pressure in wireless pricing. Strip T-Mobile out, and the rest of the sector added roughly $36 billion, in line with the day's broader recovery.
A rate hike, two down days, and a single sector supplying more than half of Thursday's rebound: the map on 17 September is a reminder that a 1.14% index gain can be a much more concentrated story underneath.
See it on the site
Sources
- AMD Jumps 7% as Semiconductor Rebound Reaches a Third Session; Broadcom Rises 3%, NVIDIA Edges Higher — Yahoo Finance (17 Sep 2026)
- Micron, Intel and other chip stocks are furthering their strong comebacks — MarketWatch (17 Sep 2026)
- Why Micron Stock Is Jumping as Intel CEO Warns on Memory Chips — Barron's (17 Sep 2026)
- Stocks surge as oil and bond yields retreat, recovering from Fed-induced sell-off — CNBC (17 Sep 2026)
- Trump says he told Warsh to vote for hike with the rest of Fed board: 'It's not going to matter' — CNBC (16 Sep 2026)
- Federal Reserve hikes key rate for 1st time in 3 years, defying Trump demands for a cut — AP News (16 Sep 2026)
- Renewed Industry Competition Sparks T-Mobile US's (TMUS) Sell-Off — Yahoo Finance (17 Sep 2026)
- Berkshire Hathaway Inc. Cl B stock underperforms Thursday when compared to competitors — MarketWatch (17 Sep 2026)
New posts as they go up: subscribe to the feed, or turn on the market close email.